 Annual Report 2025-26
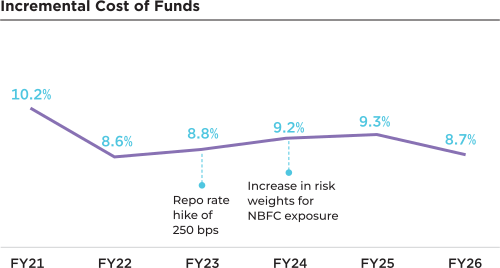
Northern Arc has steadily enhanced efficiency across the value chain through sustained improvements in the funding profile and its operating model. By progressively lowering its cost of funds, diversifying funding sources, and driving operating efficiencies, the Company strengthened its operating leverage, improved profitability and built a more scalable and resilient business.
Northern Arc has successfully managed challenging market conditions by maintaining a resilient treasury framework that reinforces financial stability and adaptability. This approach ensures uninterrupted lending operations while enabling diversification of funding sources, supporting long-term growth and sustainability.
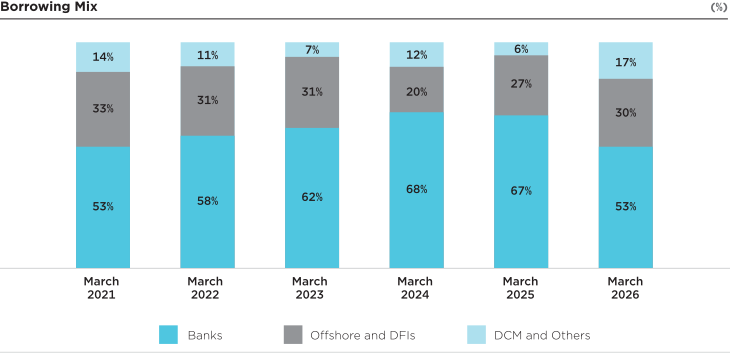
The Company continues to diversify its funding base with a clear focus on long-term and stable sources of capital. Our funding mix remains well diversified, with 30% of borrowings sourced from offshore lenders and development finance institutions (DFIs), and the balance from domestic banks and capital markets. The offshore borrowings are predominantly long-tenor in nature and remain cost-effective compared with domestic borrowings, even after fully hedging the associated currency risk. The Company maintains an almost equal mix of fixed and floating borrowings to effectively manage interest rate movements.
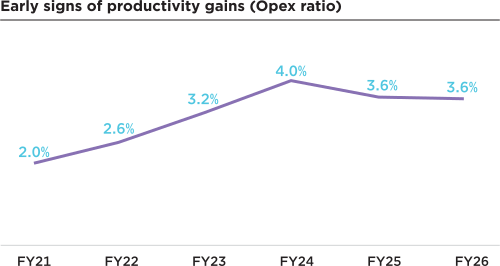
Over the years, Northern Arc has steadily expanded its presence across multiple retail lending segments to build a diversified and granular Direct-to-Customer (D2C) franchise. As part of this strategic transition, the Company made significant investments between FY21 and FY24 in expanding its physical branch network, strengthening technology platforms, and building organisational capabilities. These investments not only laid the foundation for scalable growth, they also led to the operating expenses ratio increasing from 2% in FY21 to 4% by FY24.
With the branch network maturing and operating at higher productivity levels, the benefits of these investments are now becoming evident. Improved branch throughput, greater operating leverage, and increased digital integration have contributed to a steady moderation in the operating expense ratio, demonstrating the scalability of the Company’s phygital business model.
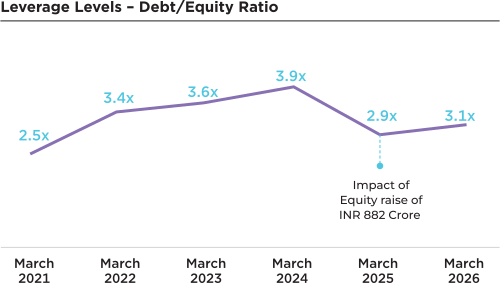
As the retail franchise continues to grow, the Company expects productivity gains and operating efficiencies to further improve and support the growing profitability, as illustrated in the graphs below.