 Annual Report 2025-26
Leveraging the insights gained from partnering with 368 Originator Partners across the financial services ecosystem, Northern Arc strategically expanded into Direct-to-Customer (D2C) lending to build a diversified and granular retail loan portfolio.
The Company identified three focus segments – MSME, Consumer, and Microfinance – where it has developed deep domain expertise through years of working alongside lending institutions and where the formal credit gap remains significant.
Northern Arc’s D2C strategy combines the strengths of physical distribution with digital capabilities through its “Phygital” business model. The Company serves its customers by leveraging a network of 432 branches to build strong relationships and provide on-ground support for origination, servicing, and collections. In addition, by partnering with 57 Digital Partners, the Company enhances customer acquisition, improves the experience, and expands access to lending across geographies. This integrated approach enables the Company to scale its business efficiently while building a well-diversified and granular lending portfolio.
| Northern Arc sectors | Market Segment we address | Products |
|---|---|---|
 Consumer Finance |
Young Indians in the mass-market and mass-affluent segments | Personal Loan, End use based financing – like Education fee etc. |
 MSME Finance |
Entrepreneurs/Small businesses focussed on trading, last-mile manufacturing & services | Loan Against Property, Supply Chain Finance, Unsecured Business loan |
 Rural Finance |
Small business owners & Rural individuals | Microfinance, micro-LAP |
Micro, Small and Medium Enterprises (MSMEs) are a key pillars of India’s economy, contributing nearly 29% to the country’s GDP and providing employment to over 278 Million people. Despite their economic significance, the sector continues to face a substantial credit gap of approximately INR 117 Lakh Crore, driven by limited access to formal financing and the diverse funding needs of small businesses.
Recognising this opportunity, Northern Arc has built a comprehensive MSME lending franchise focussed on bridging the formal credit gap. Leveraging its deep understanding of the sector, the Company offers a diversified product suite comprising Loan Against Property (LAP), supply chain finance, working capital loans, and unsecured business loans, catering to enterprises across different stages of growth. Over the past four years, the business has scaled significantly through a combination of branch-led origination, digital partnerships, and data-driven underwriting, enabling the Company to deliver timely, tailored, and responsible credit solutions.
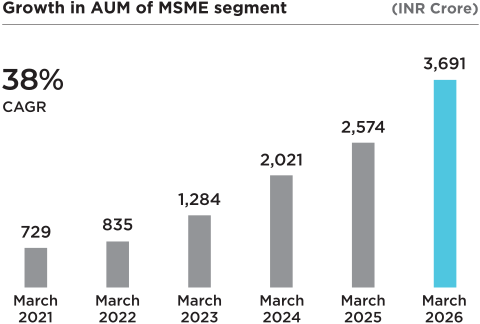
As of 31 March 2026, the Company’s MSME franchise spanned over 90 branches across seven states and one union territories and complemented by Digital Partners, extending its reach to underserved entrepreneurs across India. This integrated phygital model has enabled Northern Arc to positively impact the livelihoods of over 46,000 MSME families while deepening its presence in Tier 3 and Tier 4 markets, where access to formal credit remains limited. By combining local market knowledge with technology-enabled credit assessment and disciplined risk management, the Company continues to expand financial inclusion while building a resilient and diversified MSME portfolio.
Northern Arc launched its secured Loan Against Property (LAP) business in FY23 to address the financing needs of self-employed individuals and small businesses seeking formal credit against residential and commercial properties. The business has since expanded rapidly and, as of 31 March 2026, operates through 86 branches across seven states, supported by a team of over 550 employees.
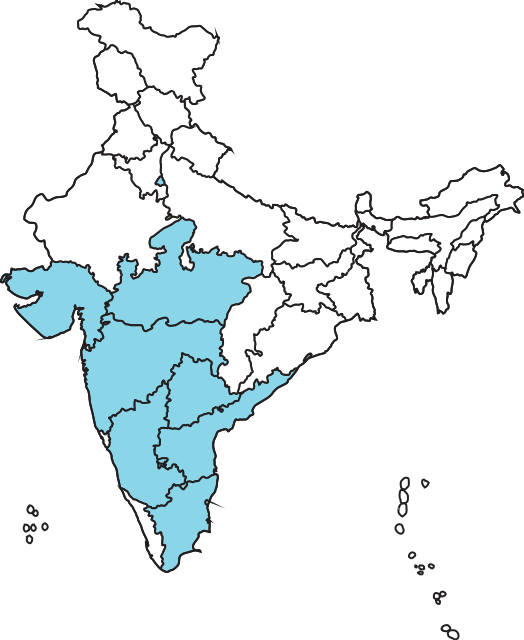 Made for representational purpose only.
| States & Union Territories | Branches |
|---|---|
| Tamil Nadu | 27 |
| Andhra Pradesh | 17 |
| Gujarat | 13 |
| Telangana | 13 |
| Karnataka | 9 |
| Madhya Pradesh | 7 |
| Maharashtra | 3 |
| Delhi | 1 |
| TOTAL | 90 |
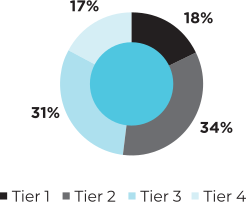
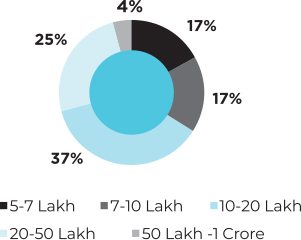
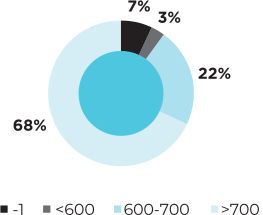
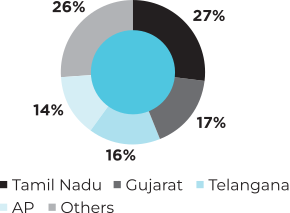
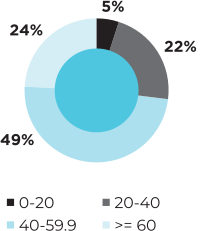
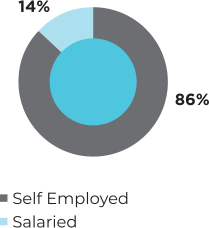
The Company offers secured LAP with an average ticket size of approximately INR 11-15 Lakh, at average interest yield of 17%-19%, catering primarily to self-employed borrowers. The underwriting framework emphasises prudent risk management, with lending focussed on customers having Bureau scores of 650 and above, maintaining conservative Loan-to-Value (LTV) ratios of less than 50% and a Fixed Obligation to Income Ratio (FOIR) capped at 50%. As of 31 March 2026, the LAP portfolio comprised over 16,000 customers with an AUM of INR 1,651 Crore, reflecting the Company’s disciplined approach to building a high-quality secured lending portfolio.
During FY26, the business demonstrated steady and resilient growth. Despite macroeconomic headwinds, our disciplined approach to portfolio management, coupled with continued investments in digital capabilities and collections infrastructure, strengthened our operating foundation and positioned us for sustainable growth.
A small portion of the Micro-LAP portfolio experienced spillover effects from stress in the microfinance sector, which impacted collection efficiency during the first half of the year. The Company placed a strong emphasis on strengthening its collections capabilities, and as collection performance in the MFI portfolio improved, the Micro-LAP portfolio also witnessed a corresponding recovery. Collection efficiency improved from 97.6% in September 2025 to 99.0% by March 2026.
Northern Arc, as part of its strategy to build a comprehensive MSME financing platform, follows a customer-centric approach by curating credit solutions across invoice financing, term loans, WCTLs, and more. The invoice financing business is largely technology-driven, leveraging client portals and loan management systems to ensure seamless transaction processing and the ability to handle high invoice volumes.
The overall business catered to around 100 clients, with a closing AUM of INR 762 Crore diversified across sectors such as solar, EVs, logistics, manufacturing, pharma, and chemicals. In addition to generating high-quality lending opportunities, this segment also creates a strong pipeline of investment opportunities for the Group’s Fund Management business, with eligible enterprises being financed through the Emerging Corporate Bond Fund.
The segment places significant emphasis on sustainable financing, which contributed more than 30% of the overall AUM.
Northern Arc also provides merchant loans to MSMEs through a network of Digital Partners under the First Loss Default Guarantee (FLDG) model. This partnership-led approach enables the Company to leverage the sourcing and distribution capabilities of digital platforms while maintaining disciplined risk management through aligned credit-risk sharing arrangements.
The portfolio continued to witness healthy growth during the year, with Assets Under Management (AUM) increasing by 31.2% year-on-year to INR 1,078 Crore. Backed by robust underwriting, continuous portfolio monitoring, and the FLDG framework, the business generates a healthy net yield, after credit costs, in the range of 15%–16%, underscoring its attractive risk-adjusted return profile.
Through its Consumer Finance business, Northern Arc caters to the financing needs of underserved aspiring young Indians in the mass-market & mass-affluent segments enabling them to meet a wide range of personal financial requirements through its digital lending business model. Launched in FY16, the Digital Lending business has evolved into a key pillar of the Company’s retail lending strategy, built on the principles of collaborations with Digital Partners, supported by its digital platform nPOS, digital data driven underwriting and risk based processes.
The Company collaborates with a diverse ecosystem of fintechs, NBFCs, business correspondents, payment platforms, educational institutions, and other digital-first originators to underwrite and disburse loans directly to end customers. This partnership-led approach enables Northern Arc to expand the company’s lending portfolio while maintaining a capital-efficient operating model. It leverages RBI’s Digital Lending Guidelines to take First Loss Default Guarantee upto 5% from Digital Partners. This risk-sharing mechanism aligns partner incentives with portfolio performance, strengthens credit discipline, and enhances the resilience of the company’s lending portfolio.
nPOS, Northern Arc’s proprietary digital lending platform, delivers a seamless, end-to-end experience. Equipped with automated decisioning, robust risk guardrails, and straight-through processing capabilities, nPOS enables loan approvals and disbursements within minutes, while ensuring strong credit discipline. The platform has the capability to process 15,000-20,000 loans every day, providing the scale, speed, and operational efficiency required to serve a rapidly growing customer base, while maintaining high standards of governance and risk management.
nPOS
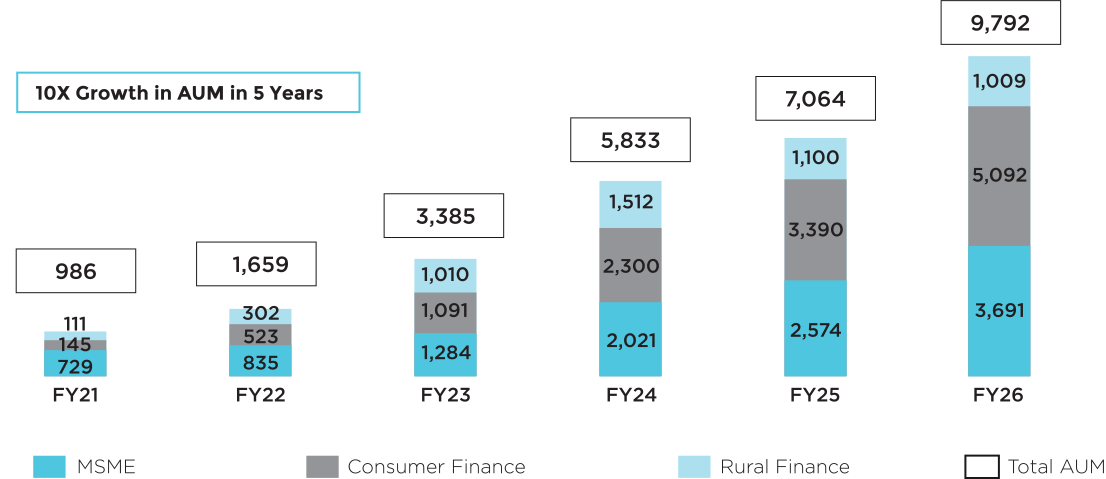
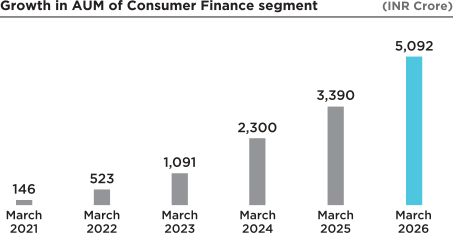
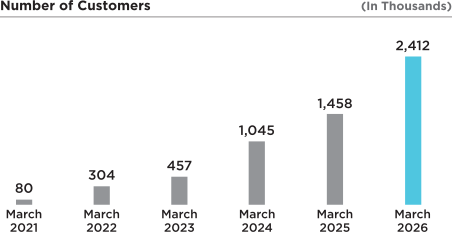
Consumer Finance recorded strong growth over the past five years, with AUM reaching INR 5,092 Crore, driven by the expansion of digital partnerships. The business also benefited from an evolving regulatory framework that has enhanced transparency, clearly defined the roles of fintechs and lenders, and strengthened the foundation for sustainable growth in digital lending.
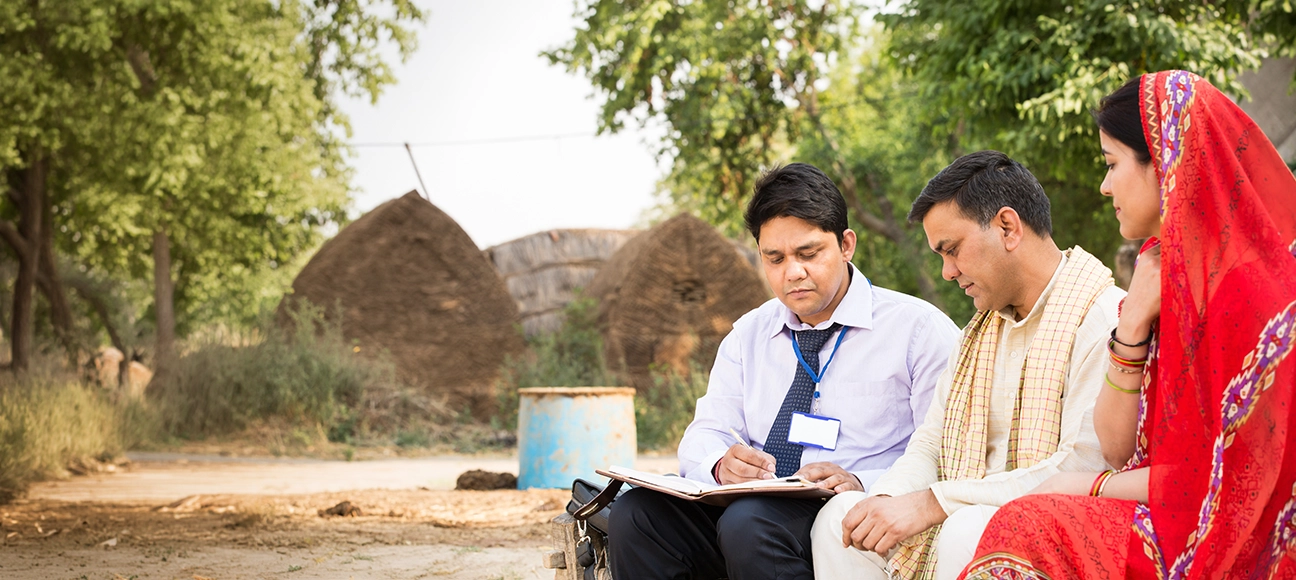
Northern Arc offers microfinance loans directly to underserved individuals through its Rural Finance business, which is operated by its dedicated subsidiary, Pragati Finserv Private Limited, acting as the Company’s exclusive business correspondent. Pragati manages the entire lending lifecycle – from customer sourcing and origination to servicing and collections – across rural and semi-urban India, with a focus on income-generating activities, small business financing, and agricultural value chains.
While the Company leverages both Individual and Joint Liability Group (JLG) model for customer sourcing and community engagement, every loan is individually underwritten using NuScore, Northern Arc’s proprietary scorecard, supported by technology-led credit assessment. This approach combines the efficiency of group-based sourcing with the rigour of individual credit underwriting, enabling responsible lending, better risk selection, and improved portfolio quality, while expanding access to formal finance in the underserved rural markets.
Following rapid industry-wide credit expansion, the Microfinance sector witnessed elevated borrower over-leveraging and asset quality stress. Anticipating these risks, Northern Arc proactively moderated portfolio growth from March 2024 while strengthening underwriting, portfolio quality, and risk management.
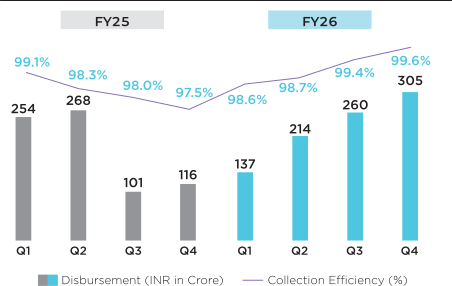
As the microfinance industry navigated a period of stress arising from borrower over-leveraging, the Company calibrated disbursements and prioritised portfolio quality over growth. It strengthened its collections infrastructure, enhanced field-level recovery capabilities, and intensified portfolio monitoring to preserve asset quality. These focussed interventions resulted in a steady improvement in collection efficiency from September 2025 onwards, reaching 99.6% by March 2026.
With portfolio performance stabilising and credit quality improving, the Company progressively resumed disbursements in a measured manner. By the fourth quarter of FY26, monthly disbursements had recovered to approximately INR 100 Crore, returning to pre-crisis levels while maintaining a disciplined approach to underwriting and risk management.
Further strengthening the resilience of its Rural Finance portfolio, the Company commenced availing coverage under the Credit Guarantee Fund for Micro Units (CGFMU) for all eligible disbursements from March 2025 onwards. As of 31 March 2026, 84% of the Microfinance portfolio was covered under the CGFMU scheme, providing an additional layer of credit protection, supporting prudent risk management, and enhancing the overall resilience of the portfolio.
During the year, the Company further strengthened its physical distribution network by adding 66 new branches, taking its total branch network to 342. This expansion reinforces Northern Arc’s MFI lending strategy by bringing credit closer to customers, enhancing last-mile origination, servicing, and collections capabilities, and deepening relationships with the local communities, supporting responsible lending while creating a scalable platform for sustainable, long-term growth.
The Company refined its origination strategy to align with the evolving regulatory guardrails and changing market dynamics. The focus shifted towards higher-quality borrowers with stronger repayment capacity and higher average ticket sizes, while maintaining prudent underwriting standards to mitigate customer over-leveraging. This disciplined approach has strengthened portfolio resilience and positioned the business for sustainable, risk-calibrated growth.